
I’m putting together a Hall of Fame of my best closed positions – which I should have completed sometime this week.
A preliminary scan highlights some trends that I think you might find interesting.
For one, almost all of my closed positions are gold miners/developers – and the only royalties/streamers are companies that have been acquired.
For the most part, royalties/streamers are long term value creators that you probably never want to sell. Of course, there’s a price you’d want to sell any asset, but for most of these royalty firms, you’d have to see a crazy price spike or a massive change in the business model to want to sell.
So I tend not to sell royalty firms completely. At times I recommend taking profits to rebalance your portfolio, but I think you want to hang on to your royalty positions.
But sometimes they get acquired…
In fact, almost ALL of my closed positions have been acquired!
That makes sense if you think about the niche that my research focuses on.
I’m not covering gold majors or ETFs. There are literally dozens of analysts covering big gold miners like Barrick and Newmont. There’s not a stone unturned with regard to those companies.
That means I’m focused mostly on small cap firms that are outside of the scope of Wall Street analyst coverage.
I have a definite information edge in this small part of the investment world because I’m one of the few analysts paying real attention to it.
Most of these firms are pre-revenue or in the awkward stage between first production and full production.
Besides myself, the only other people taking a professional look into these firms are buy-side analysts at large gold firms.
As I’ve said many times: the only way for these large miners to stay in the business of mining is to continually re-fill the hopper with exploration and development stage projects.
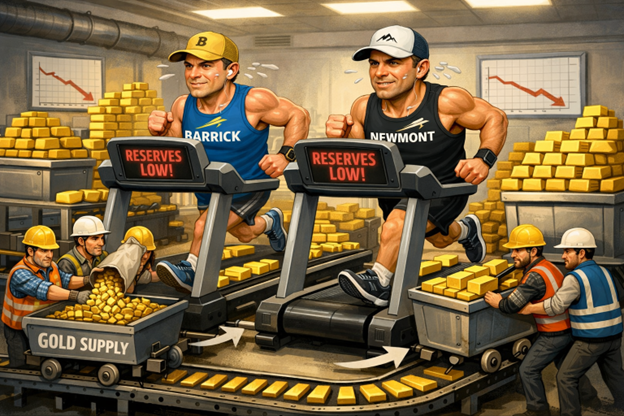
Sometimes that means doing their own exploration and development, but it usually means they go looking for existing early-stage gold stocks to acquire.
The good news: when a company gets acquired, it’s typically at a premium to the prevailing stock price.
The bad news: when a company gets acquired, you either get shares of the new parent company (which means you no longer have a direct benefit of owning the smaller company, because the parent company’s other projects are mixed into the value) – OR you get cash.
Either way, you are no longer able to capture the full upside of the smaller company’s future valuation.
As investors in this space, there’s not much we can do to avoid seeing our best companies acquired.
On the bright side, towards the end of a bull run in gold stocks, we typically see large companies massively overbid on their acquisitions. That’s one of the hallmarks telling you we’re near the end: gold majors will bend over backwards and go into debt to buy smaller gold projects.
It’s usually a disaster for the shareholders of these large firms – and a bonanza for the juniors.
But we’re not there yet. Not even close.
Later this week I’ll post my full Hall of Fame, and I’ll run through how our biggest winners panned out.
Best,
Garrett Goggin, CFA, CMT
Lead Analyst and Founder, Golden Portfolio